Coffee & Learn for Real Estate Agents.
Ben Drummer invites you to a 30-minute Thursday session on what keeps deals on track. Coffee and bagels provided. Seating is limited, so reserve your seat for each session you'd like to attend.
Questions or a buyer scenario? Reach Ben directly.

In person at our Cincinnati office.
Cohen Mortgage
4680 Cooper Rd., Suite B
Cincinnati, OH 45242
Thursdays, 10:30–11:00 AM ET. Coffee and bagels provided. Seating is limited, so reserve your seat for each session you'd like to attend. Have a buyer scenario? Bring it to Ben.
Five sessions through December.
Each session is a 30-minute take on something that shows up in files every week. Agents walk out with a short checklist and the questions to ask early.
Variable Pay Buyers
Overtime, bonus and commission: what underwriters look for.
Two buyers with the same paycheck can look very different to an underwriter when part of it varies. We cover how overtime, bonus and commission pay is read, and the questions to ask before your buyer writes an offer.
- History counts: underwriters look for a track record of the variable pay, not just this year's stubs.
- Direction counts: pay that dropped has to have leveled off, and FHA looks at the most recent year too.
- Job and pay-plan changes during the contract get caught when employment is re-verified before closing.
When Family Co-Borrows
Keeping parent-backed deals on track.
More buyers are bringing a parent onto the loan. That parent isn't a reference; they're a borrower. We cover what a non-occupant co-borrower signs up for, how title works by program, and how to keep these files moving.
- A non-occupant co-borrower signs the note and shares full liability, and their credit, income and debts are reviewed.
- Title rules differ: Fannie Mae allows them on or off title, while FHA requires every borrower to take title.
- Anyone with an interest in the sale, including the seller, builder or real estate agent, can't fill the role.
Appraisal vs. Inspection
Two reports, two jobs, and what to do when value comes in short.
Buyers mix these up, and that confusion shows up at the worst time in a deal. We cover who each report serves, what an appraisal can't consider, and how a reconsideration of value really works.
- The appraisal gives the lender a market value; the inspection tells the buyer about condition.
- A reconsideration of value works when relevant information was missed, and it goes through the lender.
- Winter buying in Cincinnati: access, utilities and the roof and furnace deserve extra attention.
Why Deals Fall Apart in Underwriting
The usual suspects, from the underwriting side.
Most files that blow up late had warning signs early. We walk through the issues that sink deals after the contract, and how agents can spot them before they cost a closing.
- New credit after the credit report gets found, verified and counted.
- Large deposits and earnest money need a paper trail the underwriter can follow.
- The same file can get a different answer at a different lender, which is why a broker shops more than one.
Second Jobs, Side Gigs & Self-Employed Buyers
Why the history decides what counts.
A second job or a side business can count, but the history behind it decides how. With tax season ahead, we cover what to ask buyers now so the income they're counting on is income an underwriter can use.
- Second-job income needs a track record; FHA looks for two uninterrupted years of part-time work.
- Owning a quarter or more of a business makes a buyer self-employed, and the tax return drives the numbers.
- Gaps in the last year and brand-new side gigs get extra scrutiny, so ask early.
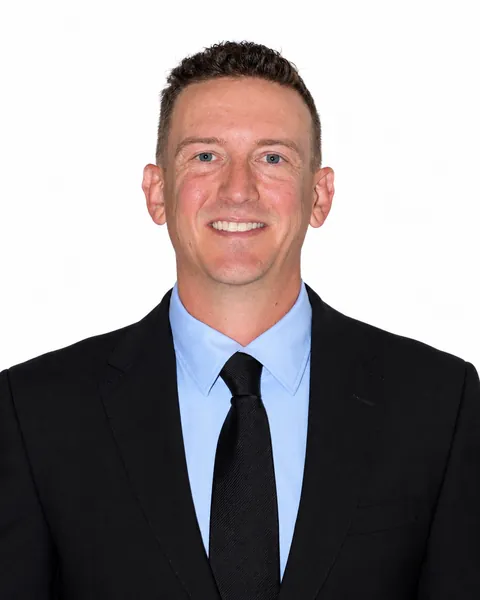
He brings over two decades of underwriting and lending to every session. He turns what shows up in real files into the questions agents can ask early.
Pick a Thursday.
Choose one or more upcoming sessions below. You'll get a confirmation email with the office address and a reminder the day before.
Questions? Call Ben at (513) 884-3048 · or email [email protected]
Have a buyer scenario?
Questions or a buyer scenario? Reach Ben directly at (513) 884-3048 or [email protected], at the session or ahead of time.